The ASX 200 finished the day down 56 points to 8,728, or 0.6% lower, off its lows for the day, but weighed down by the banking sector taking its cue from the U.S. bank results last night. The Big Bank Basket fell to $262.71, with CBA down 2.2% after its AGM and WBC down 1.3%. Financials generally were weaker, with MQG down 0.8%, and the insurers slipping away slightly too. QBE dropped 1.7%, and IAG was also falling a similar amount. The REITs were mixed, with GMG up 3.6%, although others slipped. VCX was down 0.4%, and GPT was down 0.9%. Industrials, too, were a little weaker, with CPU down 0.6%, QAN falling on higher oil prices, and the healthcare sector relatively unchanged. Retail stocks were patchy, with WES up 0.6%, JBH up 0.6%, but APE dropped 2.0%. Tech stocks rallied after a weaker start, with WTC finishing up 1.3% and TNE up 1.9%. NXT had a better day today, but the rot continued in MP1, off 1.9%.
Resources were once again on the nose, with BHP down 0.7% and RIO falling after its quarterly production update. Gold miners, too, eased off slightly, with EVN down 3.2% and NEM down 2.0%. Finally, we saw some bargain hunting appear in the lithium stocks, with PLS up 2.9% and MIN up 1.8%. The oil and gas space was better, with WDS and STO both putting on over 1%. Uranium stocks fell, led by PDN, with a disappointing quarterly production update.
In corporate news today, GLC made its debut on the ASX, trading much in line with its London listing. We also saw the GYG chairman, Guy Russo, selling 1.4 million shares, and the CBA AGM leading to some cost increases through pay negotiations.
On the economic front, nothing locally, but China reported a jump in September producer inflation on the crisis in Iran.
10-year yields ease to 5.31%. US Futures showing solid gains.
HIGHLIGHTS
- Winners: ASB, SKS, SXE, AIS, KAR, SLC, SLX
- Losers: PDN, PYC, ORA, BRE, DGT, 4DX
- Positive Sectors:
- Negative Sectors:
- ASX 200 Hi 8758 Lo 8698
- Big Bank Basket: Lower at $262.71
- All-Tech Index: Down 0.1%
- Gold: Down at $5950
- Bitcoin: Steady at US$83413
- 10-year yields: Eases to 5.31%
- AUD: Higher at 70.01.
MARKET MOVERS
- SKS +8.0% ASX price query.
- ASB +10.1% update on AUSA transaction
- SXE +6.4% data centre contractors bounce.
- KAR +6.2% crude higher.
- WBT +3.4% chips less fried.
- LGI +13.0% board and executive changes.
- MTM +8.7% recycling.
- CTT +2.9% good vibrations from hedge fund position.
- SKK +9.1% kicking again. Government agencies tapping for US election.
- PDN -9.3% quarterly disappoints.
- VGN -4.9% oil price.
- ORA -5.8% AGM presentation.
- 4DX -6.9% profit taking.
- TM1 -15.4% high grade PGM from surface.
- Yesterday’s Hero: ALV -14% – Not to be at five days!
- Speculative Stock of the Day: ID1 +34.0% Investor presentation.
- Household spending on home loan repayments across nearly all states and territories is above or near the highest it has been in more than 30 years.
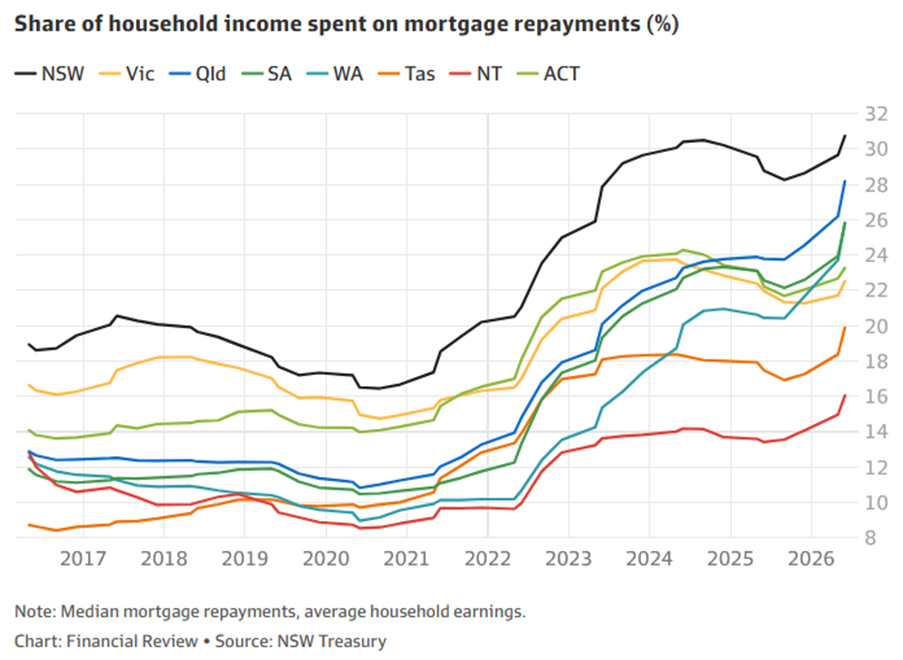
- The average NSW family in the state used nearly 31% of household income on mortgage repayments in June this year.
- China’s producer inflation swung higher last month, as escalating hostilities in the Middle East sent oil prices surging past $100 a barrel and goods related to AI became more expensive.
- Prices at the factory gate jumped 5% from a year earlier, reaching their fastest since 2022, according to data released by the National Bureau of Statistics.
- Chinese exports surge 36% as AI-related shipments boom.
- CoreWeave targets unlimited insurance money to fund AI buildout.
- The UK Chancellor, John Healey, is set to pay for budget giveaways without more borrowing.
- An employee at OpenAI, Abdulrahman Alfozan, was arrested and charged with using a hidden recording device in one of the company’s San Francisco offices.
- Aramco’s executive headquarters in eastern Saudi Arabia was hit during a missile attack by Yemen’s Houthi militants on Tuesday.
And finally..
Clarence
XXXX

